July 20, 2026
Think back to how lending worked before the modern credit score. Banks evaluated borrowers using rough demographic proxies, past repayment records from a few institutions, and gut instinct. The result was systemic misclassification, with genuinely creditworthy applicants denied and high-risk borrowers approved. When FICO introduced a standardised, behaviour-driven numerical score in the 1980s, it did not just improve lending decisions. It rebuilt the entire economics of credit.
Motor insurance in 2026 sits at an almost identical inflection point.
Today, most behaviour-based car insurance products, including leading Pay-How-You-Drive (PHYD) propositions across India, Europe, and the United States, score drivers using legacy ACB metrics: Acceleration, Cornering, and Braking events. These are the road-safety equivalent of counting loan defaults after they have already occurred. They are reactive, stripped of context, and increasingly inadequate for the intelligence the market demands.
Contextual Driver Intelligence is to motor insurance what the credit score was to lending: a shift from blunt historical proxies to granular, forward-looking risk signals.
The global UBI market was valued at $62.6 billion in 2025 and is projected to reach $567.6 billion by 2035 at a 24.8% CAGR, according to Global Market Insights. This is not incremental growth. It reflects a structural shift in how risk is assessed and priced across the world's major auto markets.
India
The Indian motor insurance market is forecast to grow from $13.19 billion in 2025 to $21.48 billion by 2030 at a 10.25% CAGR. The insurance telematics segment within India is growing even faster, at a 21.4% CAGR through 2033. Crucially, India’s 2025 regulation now requires all carriers to list PAYD as a standard motor option, opening the door wide for PHYD adoption among IRDAI-approved insurers including Bajaj Allianz, ICICI Lombard, HDFC ERGO, and ACKO.
Europe
Europe held a 32.41% share of the global telematics insurance market in 2025, underpinned by GDPR-backed consumer trust and stringent road-safety mandates. An EIOPA survey found that 17% of carriers already market telematics products, with the forthcoming EU Data Act expected to formalise data-sharing rights and accelerate deployment. UK, Italy, and Germany lead regional adoption.
United States
North America accounted for 35.21% of the global UBI market in 2025, driven by widespread connected vehicle infrastructure and deep penetration of programs like Progressive’s Snapshot. Real-time driving analytics have become a standard feature of mobile insurance apps across major carriers, enabling dynamic premium adjustments at scale.
Legacy telematics platforms score three events: hard braking, sharp cornering, and aggressive acceleration. Each is a post-hoc flag, recorded after the risk has materialised. This creates four interconnected problems for insurers.
The result is a scoring system that is simultaneously unfair to good drivers and insufficient for underwriters trying to segment risk with precision.
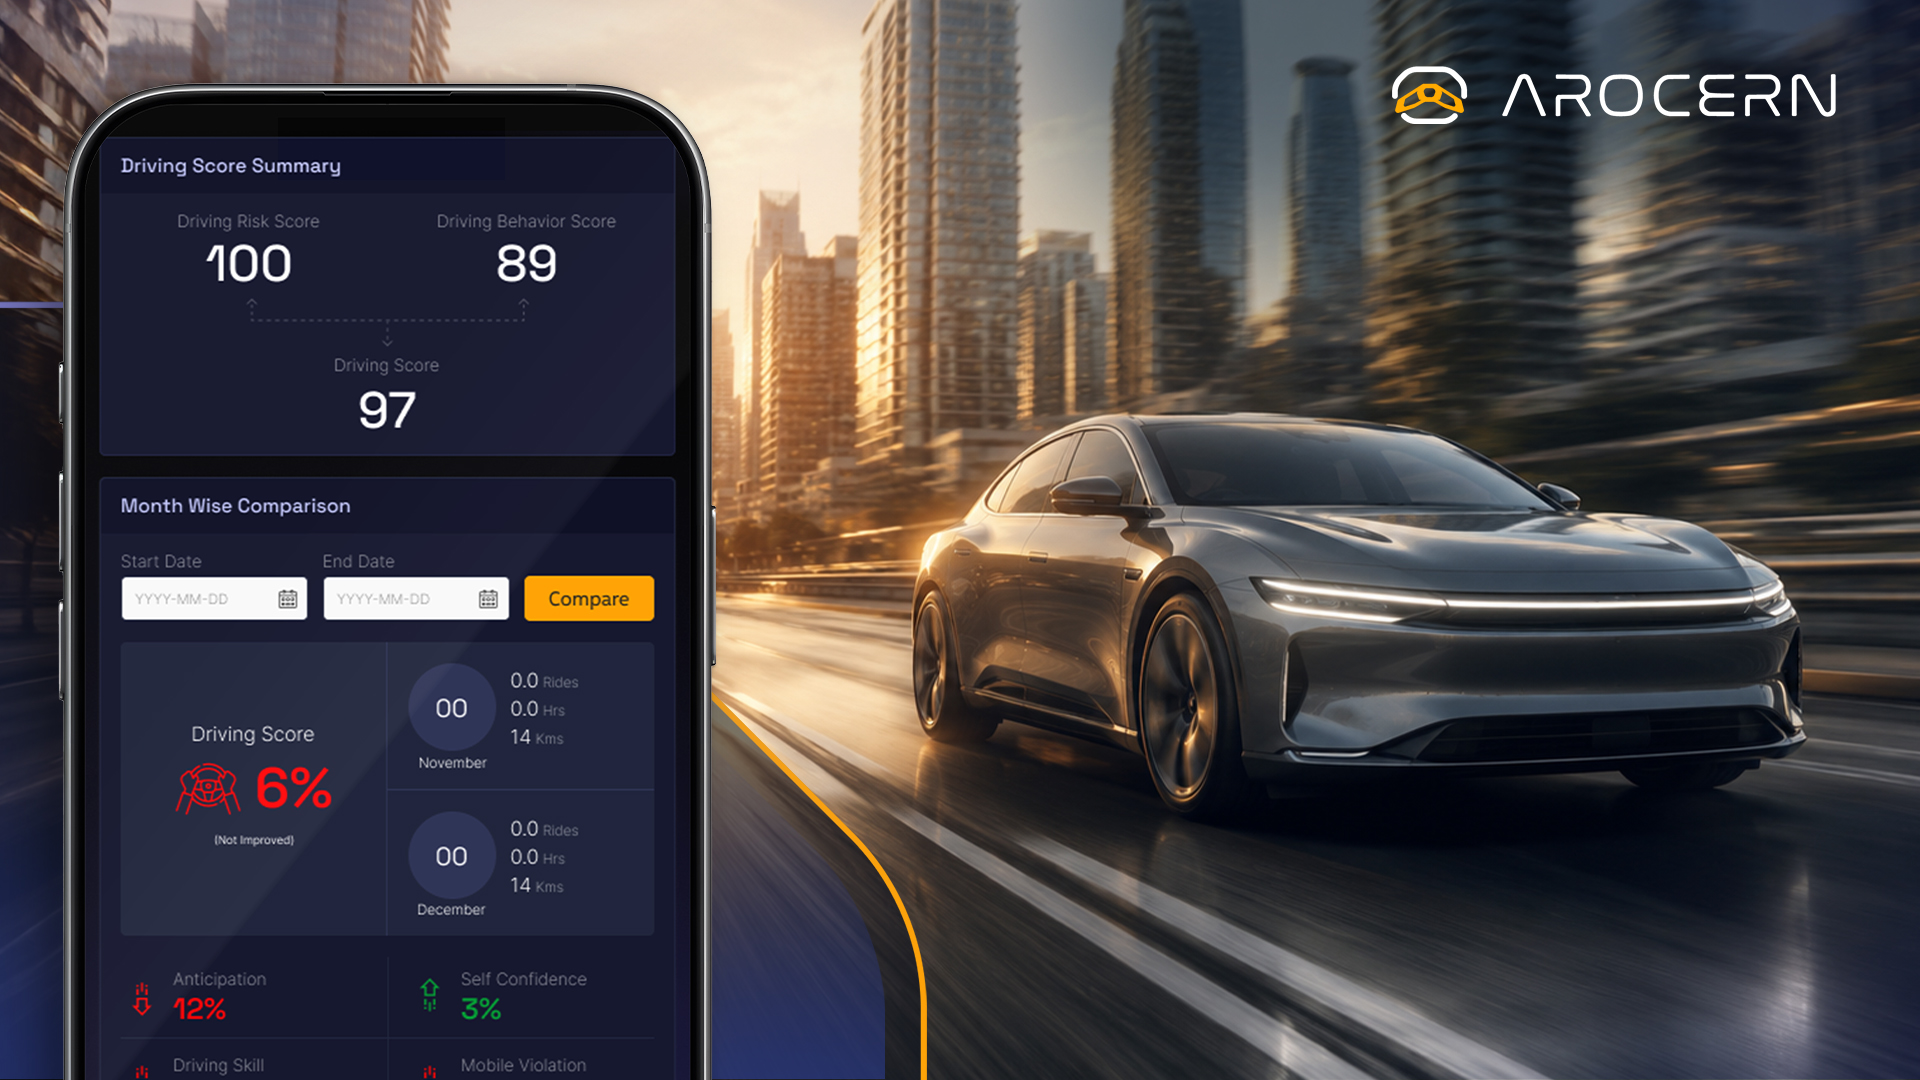
Contextual Driver Intelligence evaluates four dimensions of driver performance simultaneously: intent, anticipation, skill, and behaviour. Together, they produce a high-resolution risk profile analogous to a financial credit score, one that is dynamic, explainable, and rooted in forward-looking signals rather than historical event counts.
1. Driver Intent
Does the driver plan their journey, adjust for conditions, and demonstrate awareness of their environment? Intent analysis evaluates patterns across multiple trips to distinguish habitual prudence from episodic compliance. A driver who consistently reduces speed before school zones is displaying a qualitatively different risk profile from one who slows only when a child is visible.
2. Anticipation: The 200-Metre Advantage
Traditional telematics flags a hard braking event at the moment it occurs. Contextual intelligence identifies the absence of anticipatory deceleration 200 metres before the point of risk, whether that is a sharp curve, a congested junction, or a pedestrian-heavy zone. This distinction is fundamental. It separates the driver who reacts from the driver who anticipates, and it is the anticipatory driver who files fewer claims.
Cambridge Mobile Telematics validated this principle: its DriveWell platform, which incorporates anticipatory feedback loops, achieved a 20% reduction in claim frequency among enrolled drivers. That is the commercial proof point that anticipation-aware scoring delivers measurable loss ratio improvement.
3. Skill
Skill is the capacity to execute the right driving decision under pressure. A high-skill driver navigates a wet roundabout differently from a low-skill driver covering the same route in identical weather. Skill scoring analyses vehicle dynamics in context: how the driver manages weight transfer, maintains lane discipline, and responds to unexpected inputs. It is the dimension that credit scoring equivalents call financial literacy, the underlying capability that predicts future behaviour.
4. Behaviour: Context-Aware, Not Context-Blind
Contextual intelligence differentiates between a braking pattern on an open highway and the same pattern in a pedestrian-dense urban centre. Risk is relative to environment. A driver maintaining 60 km/h on a school road during drop-off time represents a categorically different risk from one maintaining the same speed on an empty rural motorway. Behaviour scoring that ignores this distinction is not risk scoring. It is noise generation.
The best driver score is not the one with the fewest events recorded. It is the one that most accurately predicts the next five years of claims.
Improved Loss Ratios
AI-driven underwriting enhancements have been shown to improve risk segmentation accuracy by up to 25%, according to Technavio’s 2025 analysis of AI deployment in insurance. When that accuracy is applied specifically to driver risk scoring, the downstream effect is a measurable reduction in loss ratios through the elimination of misclassified risks at both ends of the distribution: underpriced high-risk drivers and overpriced safe ones.
Regulatory Compliance Through Explainability
Insurance regulators across India (IRDAI), Europe (EIOPA), and the US (NAIC) are increasingly requiring that pricing models be explainable, auditable, and demonstrably fair. A contextual score can generate a specific narrative for every premium decision: the score was adjusted because of inadequate speed reduction on high-risk curves on three separate occasions. That is an audit trail. Legacy ACB black-box scores are not.
Retention Through Fairness
When a customer understands exactly why their premium changed and is shown a concrete path to improving it, the dynamic shifts from adversarial to collaborative. The insurer becomes a road safety partner rather than a pricing mechanism. This is the engagement model that drives the retention rates and net promoter scores that telematics-first carriers in Italy and the UK have demonstrated over the past decade.
Hardware-Free Scalability
Pure-software SDK deployment eliminates the logistics, cost, and compliance overhead of OBD-II device programmes. The scoring engine runs within the insurer’s existing mobile application. Deployment across an entire book of business becomes a software release cycle, not a hardware logistics operation.
India: From Compliance to Competitive Advantage
India’s 2025 regulatory mandate positions PAYD as a baseline standard. The carriers that move from baseline PAYD to contextual PHYD scoring will have a clear competitive advantage in a market that is simultaneously growing at 10% annually and producing over 150,000 road fatalities per year. The case for contextual scoring in India is not just commercial. It is a road safety imperative.
Europe: Precision Pricing Meets GDPR
Europe’s regulatory environment demands both accuracy and transparency. Contextual driver intelligence delivers both. Explainable AI scoring satisfies the letter and spirit of GDPR’s fairness requirements while giving carriers in the UK, Italy, and Germany the risk granularity to compete on pricing precision rather than product commoditisation.
United States: The Next Layer on Top of Snapshot
US carriers have proven the commercial model: Progressive’s Snapshot programme has demonstrated that behaviour-linked pricing builds loyalty and improves portfolio performance. The next competitive frontier is the shift from reactive event-counting to anticipatory intelligence. The carriers that make that transition first will define the next decade of UBI differentiation.
Credit scores did not just make lending more accurate. They made credit more equitable, more accessible, and more commercially sustainable. Contextual driver scoring is poised to do the same for motor insurance.
The shift is not about collecting more data. Every telematics platform collects data. The shift is about evaluating the right signals: intent, anticipation, skill, and behaviour in context, not G-force events in isolation.
The global UBI market is growing at nearly 25% per year. The insurers who will own that growth are not the ones with the most sensors. They are the ones with the most intelligent scores.
